Mid-Year Benefits Reviews for Growing Headcount
Rising health costs make mid-year benefit reviews essential for growing companies.
Health benefit costs are climbing at their fastest pace in more than 15 years, and that single fact changes what inaction costs a growing company. It's a bet that the cost environment will stay forgiving long enough to deal with later, and that bet is getting worse every cycle. Mercer's analysis puts this as the fifth straight year of elevated cost growth, following roughly a decade of milder increases: it is the new baseline, and the employers who manage plan design actively are pulling further ahead of those who don't with each renewal.
Hiring intensifies three forces: a growing workforce pushes against the limits of its insurance pooling, its compliance obligations, and its plan design all at once. A growing company still sitting in a fully insured small-group plan is in the part of the market where that concentration is most severe, and every employee added mid-year without a plan review deepens that exposure.
Most growing companies are running benefit programs that lag their headcount by a stage or two. By then the decision window has already closed for the year. Mid-year is the point where that drift is still cheap to correct, and treating it as a quiet stretch between renewals is how companies let a fixable problem become an expensive one.
How plan design drifts out of alignment as headcount grows
A benefits plan built for a twenty-person company doesn't scale cleanly to sixty people. The mismatch doesn't announce itself with a single bad outcome. It builds quietly, plan year after plan year, until renewal forces the company to confront costs and gaps that have been accumulating the whole time.
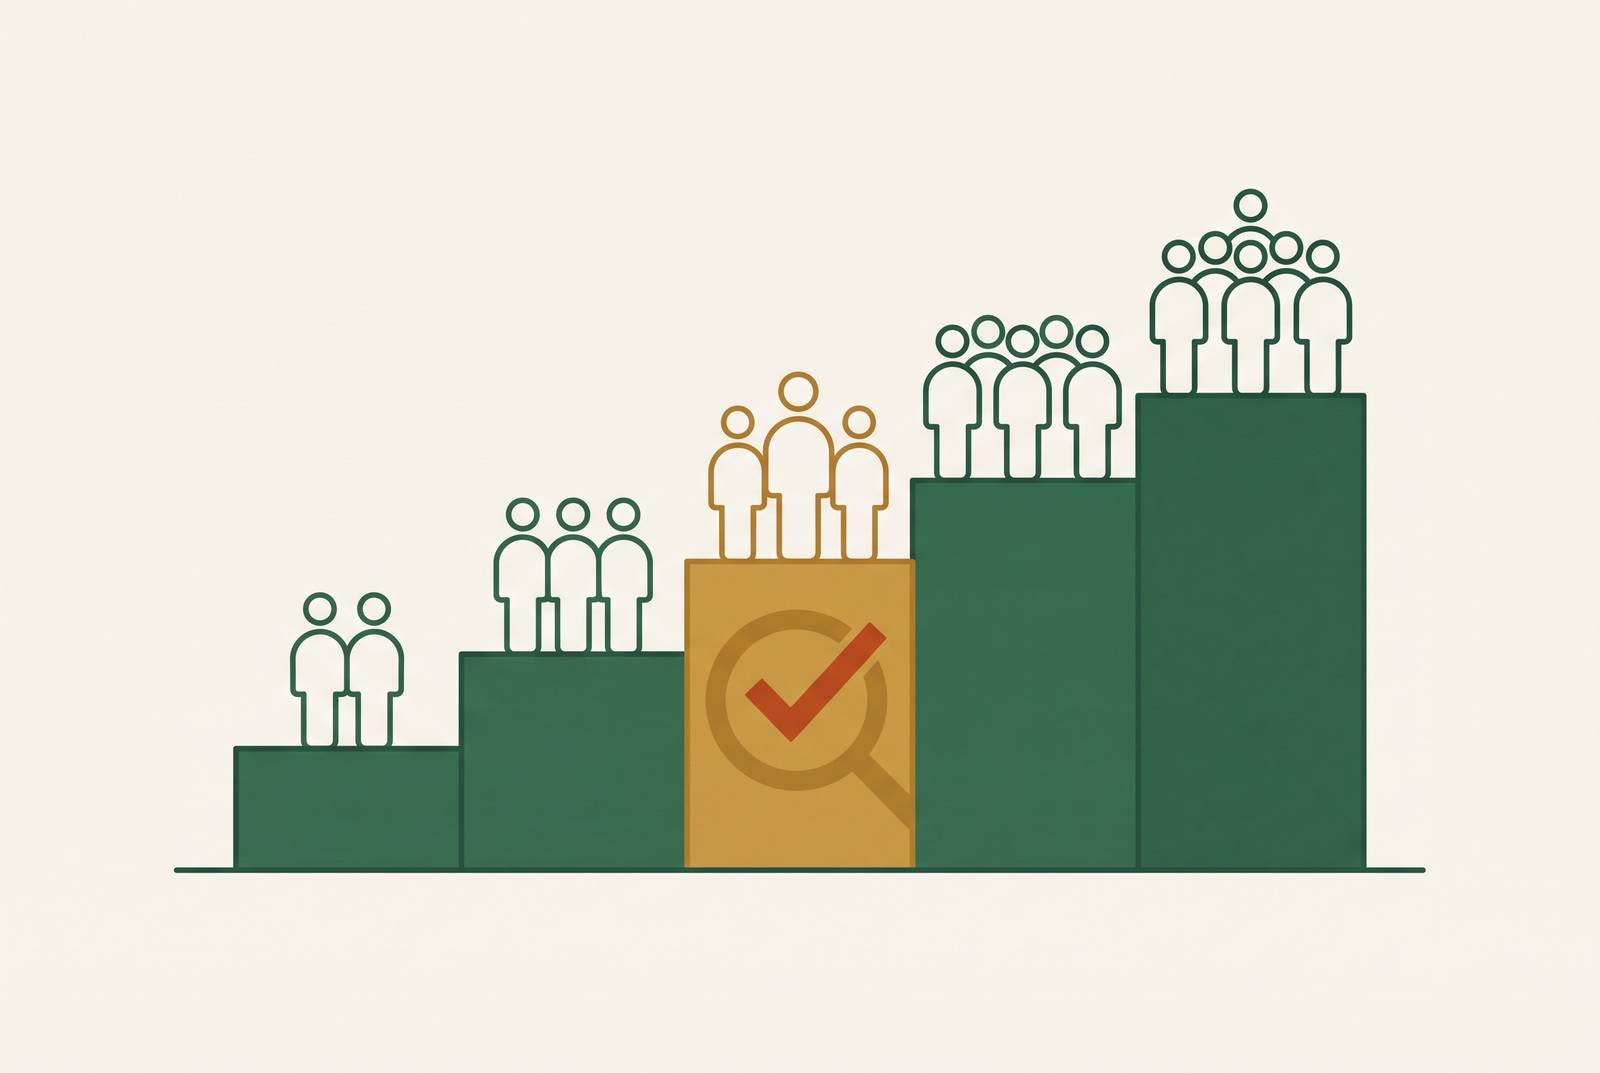
Hotaling's four-stage framework gives a useful way to think about this drift, without needing to treat the stage boundaries as fixed rules. Stage 1 programs are built to give a workforce access to basic coverage, not to compete for talent or manage cost with precision. Most growing companies sit somewhere in between, and the honest exercise is figuring out, with a benefits advisor, which stage actually fits the current headcount.
Headcount growth changes more than the number of people enrolled. A company that crosses one of these thresholds in April and waits until November's open enrollment to do anything about it has left months of savings on the table that a mid-year check would have caught.
Voluntary and supplemental benefits show how concretely this drift plays out. Accident coverage, critical illness coverage, and hospital indemnity plans add real, employee-perceived value at close to no cost to the employer, and Hotaling's framework treats their presence as a marker of a Stage 3 program. Companies that haven't added them by the time their headcount justifies it are leaving value on the table that would cost almost nothing to capture.
Low utilization data at mid-year compounds the problem by disguising it. What looks like a well-run plan at mid-year can be a communication failure wearing the mask of one.
The compliance obligations that appear silently when headcount crosses key thresholds
Compliance obligations in benefits are tied to headcount, not the calendar, and they activate the moment a company crosses a specific threshold, whether or not anyone at the company notices. Nobody watches headcount as a trigger for legal obligations, so the obligations activate quietly and stay unmet until an audit or a penalty notice surfaces them.
ACA affordability and reporting rules are the clearest federal example. The IRS affordability percentage for plan years beginning in 2026 has been set at its highest level yet, and that figure directly determines how much employees can be asked to contribute toward their premiums before the plan runs afoul of the law. Getting that calculation wrong carries real cost. Lockton's 2026 schedule of DOL penalties and Apex Benefits Group's compliance checklist lay out these figures in detail, and the amounts exist because the obligations are specific.
None of this responsibility transfers just because a company outsources plan administration. Carriers process claims, but the employer stays legally on the hook for maintaining the summary plan description document and filing the required annual plan filing, no matter who else touches the plan day to day.
Hiring across state lines adds a second layer on top of the federal one, and each new state can bring its own rules. California offers a concrete example for 2026: fully insured large-group plans renewing on or after January 1, 2026 must now include IVF coverage, a requirement that wasn't on the books at many employers' previous renewal.
A federal labor regulator has also named its 2026 enforcement priorities, and they include cybersecurity, barriers to mental health and substance use disorder benefits, protecting benefit distributions, retirement asset management, surprise billing, and criminal abuse of contributory benefit plans. A mid-year plan review that produces updated documents and a written record of deliberate compliance decisions builds exactly the kind of audit trail that matters if any of these areas draws regulatory attention. Modern benefits administration platforms can automate much of this work, generating ACA forms directly from payroll data, triggering COBRA notices the moment someone is terminated, and keeping a digital record of every action taken. None of that automation helps if the data behind it doesn't reflect the company's actual current headcount and enrollment.
Why PEO pooling, which solved this problem at twenty employees, stops solving it at scale
The PEO arrangement that gave a fifteen-person startup access to large-group insurance rates and ready-made compliance infrastructure starts working against the company once it has enough employees and enough claims history to negotiate its own terms. The company has outgrown the specific problem the PEO was built to solve.
The value of pooling is strongest exactly where a company has the least leverage of its own. The same guide points out that the recruiting benefit is real too, since access to large, recognizable national carriers lets a small company close offers against better-funded competitors who'd otherwise win on benefits alone.
That arithmetic changes as the company grows. A company that has grown large enough to qualify for a level-funded or self-funded arrangement is often still paying PEO rates for a pooling benefit it no longer needs.
Leaving isn't simple, and that's by design. PEOmetrics' 2026 exit playbook breaks that cost into three layers: one-time exit costs, temporary overlap costs, and risk-driven cleanup costs, and across its broader material it recommends negotiating exit terms before signing.
PEOs have a demonstrated record of lowering turnover, supporting faster growth, and meaningfully reducing shutdown rates, and a company that exits too early can sacrifice genuine operational support it still needs. That argument holds for companies that haven't built internal HR capacity yet or don't have enough claims data of their own to negotiate independently. The PEO decision is about whether this specific company, at this specific headcount, still needs what the PEO is charging for, and the mid-year review is when that math should be rerun, because the answer changes as headcount grows and the company's own claims history accumulates.
How benchmarking mid-year turns headcount growth into a carrier negotiating asset
Added headcount gives a company more leverage with carriers than it had at its last renewal, but that leverage only matters if the company puts it to work before the renewal conversation starts, not during it. Carriers negotiate against data. A company that shows up to renewal with competitive quotes and current claims data in hand is negotiating from a different position than one that shows up only with last year's plan document.
Benchmarking is the mechanism that turns headcount into leverage. A competitive quote is what moves a carrier, and the benchmark is what tells the company it's worth going out and getting one.
Mid-year is the right time to do this work precisely because it leaves enough runway to run a real competitive process before renewal arrives. Waiting until sixty or ninety days out compresses everything: there's less time to gather competing quotes, less time to run the actuarial analysis that supports a funding-model change, and less time to communicate any plan changes clearly to employees before they have to make enrollment decisions. Every one of those compressions makes the eventual decision worse.
The same benchmarking exercise is the natural moment to ask whether the company's current headcount and claims profile would support a level-funded or self-funded arrangement at lower total cost. Hotaling's strategy framework treats the choice between staying fully insured and moving to self-funding as the single highest-leverage decision in mid-market benefits strategy, and it notes that most companies make this choice by default, staying fully insured well past the point their data would support a change.
Plan design decisions that used to be set-and-forget now need active attention too. Coverage for GLP-1 medications is the clearest current example: these drugs now account for a meaningful share of prescription spending at large self-funded plans, and a company that simply carries forward last year's plan document is making a real cost decision by default. These choices affect cost and employee experience all year, and mid-year is the time to decide them deliberately.
Running a mid-year benefits review
A mid-year benefits review covers four areas: plan design fit, compliance posture, cost benchmarking, and delivery model. It is not a single pass through enrollment numbers to make sure the headcount matches payroll.
Plan design fit means checking whether the current plan menu actually matches the workforce sitting in it today, not the workforce that existed at the last renewal. Voluntary benefits are a fast fix to check for here: adding accident, critical illness, or hospital indemnity coverage takes little more than a conversation with the carrier, and Hotaling's framework flags these as commonly missing at exactly the growth stage where most companies need them.
Compliance posture means mapping current headcount against every federal and state threshold that might have been crossed, confirming that ACA contribution levels still meet the current affordability standard, and checking that every required filing and notice is up to date, with each decision documented as it's made. If the company is approaching a threshold that would trigger large-group mandates or Form 5500 filing requirements, the review should produce a compliance calendar looking forward, not just a snapshot of where things stand today.
Cost benchmarking means pulling current plan costs and comparing them against market data for the company's industry, geography, and headcount band to see where the company sits in the cost distribution. A company sitting in the upper half of that distribution for comparable coverage has the evidence it needs to go out for competitive quotes before renewal arrives. This is also where the funding-model decision belongs: whether level-funded or self-funded arrangements are now within reach, a decision Hotaling's framework calls the highest-leverage one in mid-market benefits and the one most companies default past without ever deciding.
Delivery model review means rerunning the numbers on whatever structure the company currently uses. If the company works with a traditional broker, it means asking directly whether that broker has brought competitive benchmarking to the table or simply renewed the plan on the carrier's terms each year, since the latter is a sign it may be time for a more active advisory relationship.
Employee communication belongs inside this review, not off to the side as something to address later. If utilization data shows low engagement with a specific benefit, the review should produce a communication plan to run before the next open enrollment, not a note to revisit the issue next year.
How the right advisory model determines whether the review happens
None of this happens on its own under a traditional broker relationship, and the reason is structural. In practice, this means most mid-year check-ins under a traditional broker amount to an enrollment headcount audit, not the plan-design and cost-benchmarking work described above.
PEOs solve a different version of the same problem by removing it entirely, at a cost. The PEO's pooling benefit and its control mechanism are the same feature. A company that has grown large enough to negotiate better terms on its own still can't act on that leverage while it remains inside the PEO's plan.
An AI-native brokerage model is built to avoid both failure modes. The analysis runs continuously rather than waiting for a renewal trigger, which is what makes a mid-year review a standing practice instead of a rare event. Automated compliance monitoring across federal and state jurisdictions turns the compliance review from a manual audit into a tracked process that updates automatically as the company hires into new states. A round-the-clock employee concierge closes the communication gap that makes utilization data misleading in the first place: employees who can get real answers to benefits questions when they have them actually use their benefits, which produces cleaner data and a stronger negotiating position at renewal.
The cost structure of this model matters as much as its mechanics. A brokerage paid by carriers at no direct cost to the employer removes the fee barrier that keeps active management from happening, making the mid-year review part of the advisory relationship itself, run as a matter of course rather than as an exception someone has to ask for.